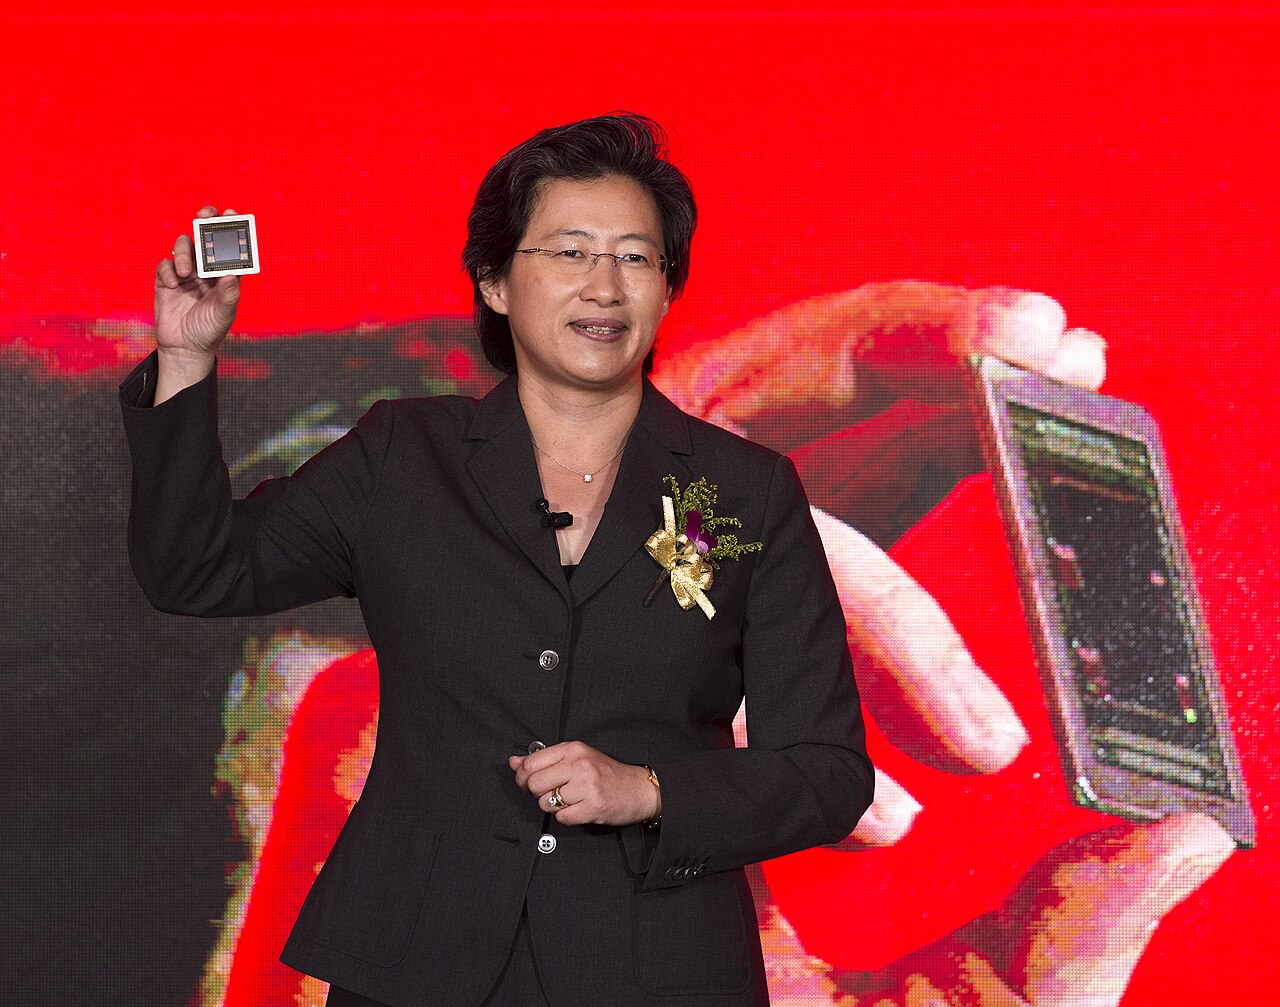
AMD reported third-quarter 2026 results on Tuesday, November 3, with revenue up 45% year over year to $13.38 billion, against $13.09 billion expected by analysts surveyed by LSEG, according to CNBC. Adjusted earnings per share were $2.09 against $1.95 expected. The year-earlier revenue figure was $9.25 billion.
The headline beat was modest. The more informative parts of the report are the shift in what AMD sells, the fourth-quarter guidance, and the decline in the consumer businesses. This post works through each, and flags where figures are our own arithmetic. For the prior quarter, see our Q2 2026 analysis.
The mix shift
Data center revenue nearly doubled from a year earlier and made up 64% of total revenue, up from 47%. Applying those shares to the reported totals gives roughly $8.56 billion of data center revenue in Q3 2026 against roughly $4.35 billion in Q3 2025. That is our arithmetic from rounded percentages, so treat it as approximate.
Data center nearly doubled; everything else stayed flat
AMD quarterly revenue split, in billions of dollars. Data center dollars are our calculation from the reported 47% and 64% shares.
Source: CNBC, November 3, 2026; derived values are our arithmetic.
The chart makes a point the headline obscures. Revenue outside data center was roughly flat, at about $4.9 billion a year ago and about $4.8 billion now by the same calculation. Essentially all of the 45% growth came from one segment.
The consumer side
The combined PC and gaming segment's revenue fell 8% year over year to $3.7 billion, and gaming revenue fell 40%. CNBC cites Counterpoint Research reporting that global PC shipments fell 4% in the second quarter from a year earlier, due to higher memory and component costs. The memory shortage is therefore a cost on the consumer side while demand for the data center products it supplies is strong, a pattern echoed in Qualcomm's results the next day (see our market analysis).
Guidance: the agentic CPU argument
AMD guided fourth-quarter revenue to about $17 billion against a $16.2 billion average analyst estimate (LSEG), and gross margin of 55% against a 55.3% average estimate (StreetAccount). The guidance beat is on revenue; the margin is marginally below expectations.
CEO Lisa Su said data center AI growth will accelerate faster than AMD projected 90 days earlier, and that she expects server revenue to double year over year in 2027. Her explanation was specific: agentic AI is "just starting," and server CPUs matter because they power virtual machines that can run for hours. CNBC reports that agentic AI demand pushed AMD shares to a record in October.
Server CPUs power virtual machines that can run for hours.
CNBC summary of Lisa Su's explanation of agentic AI demand
The analytical point is that AMD is framing its growth as CPU as well as GPU demand. Agent workloads run long and keep many sessions alive, which shifts some spending toward general server capacity. That is a company's own thesis, and the quarter's results are consistent with it but do not isolate it, because the reported figures do not split CPU from accelerator revenue.
Helios, customers and supply
CNBC reports that AMD's Helios rack-scale systems compete with Nvidia's Grace Blackwell and Vera Rubin systems, and that Meta, Microsoft, Anthropic, OpenAI and Oracle are beginning to use Helios. Meta said its Helios racks are running. Su said AMD has secured "wafers, substrates, advanced packaging, memory" for much higher growth next year.
The same report lists AMD's financial ties to customers: a $1 billion investment in Meta's equity offering, up to $5 billion committed to Anthropic, and the September agreement to acquire World Labs for $8.2 billion in an all-stock deal. Investments in customers raise a fair analytical question about how much demand is independent of the supplier's own capital, which the quarterly figures cannot answer either way.
Market reaction
Shares rose about 8% in extended trading but pared those gains as election results came in, and CNBC cites a year-to-date gain of roughly 125% to 129%, with shares having had three straight losing days before the report. Two days after the report, AMD was among the stocks that fell by double digits in the November 5 selloff.
 AMD
 NVIDIA
 Meta
 Microsoft
 Anthropic
What to watch
- Supply for 2027. Whether AMD's secured capacity matches the doubling it describes.
- CPU versus accelerator split. Whether future disclosures separate the two, which would test the agentic-CPU thesis.
- Customer concentration. How much of data center growth comes from a handful of buyers that AMD also invests in.
Because AMD, Nvidia and others now compete on rack-scale systems, hardware choice increasingly sits behind the software layer. Tools that let teams switch models and providers without rewriting their workflow, such as Metir, make that kind of hardware diversification less visible to end users.
Sources:
- AMD Q3 2026 earnings report, CNBC, November 3, 2026 (updated November 4)
- AI meltdown: Nvidia and Qualcomm drop more than 9%, CNBC, November 5, 2026
Image credits
- Hero: "AMD CEO Lisa Su 20150603" by Gene Wang, licensed CC BY 2.0, via Wikimedia Commons. Retrieved November 2026 and visually reviewed. This is a 2015 file photo of AMD CEO Lisa Su holding a chip; it does not depict the Q3 2026 report or Helios.