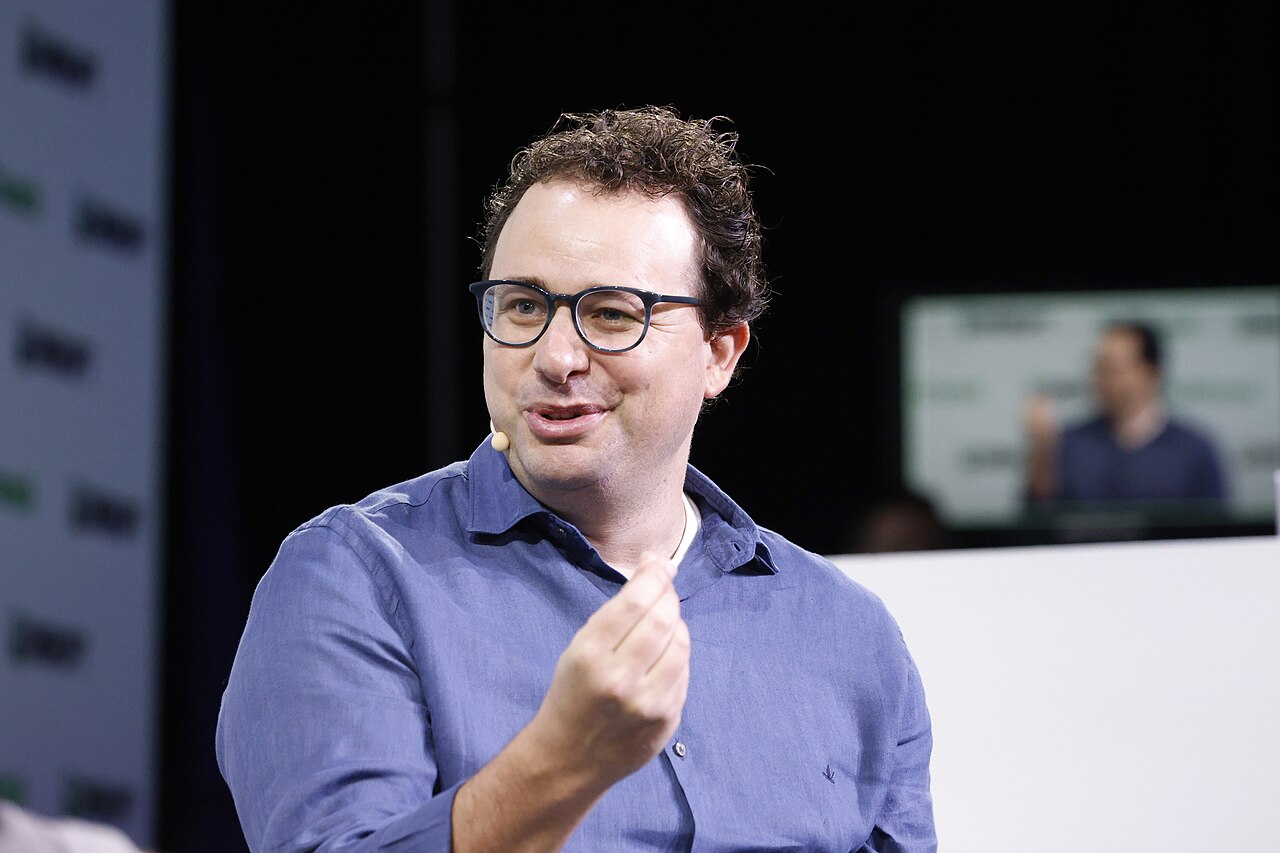
Anthropic's IPO prospectus, reported on September 28 and 29, 2026, is the first detailed look at the financial statements behind one of the most valuable private companies in the world. Reuters, which saw the document, reported that it targets a valuation above $2 trillion, more than double the roughly $965 billion mark set in the company's private funding rounds earlier this year. The listing is expected after the November 2026 US midterm elections. This piece unpacks what the leaked figures say, what they do not say, and how to read both the bullish and the cautious interpretations. It builds on our earlier coverage of the confidential filing and near-trillion-dollar plan.
 Anthropic
 IPO prospectus: the headline numbers
According to Fortune, Forbes and Reuters-sourced reports, the prospectus shows the following for fiscal year 2025:
- Revenue: about $4.59 billion, up roughly 12x (about 1,088%) from about $386 million the year before.
- Net loss: about $42 billion (approximately $41.97 billion on a GAAP basis).
- Operating loss: about $8.06 billion, widened from about $2.98 billion in 2024.
- Compute and infrastructure spend: about $7.33 billion in 2025, roughly three times the 2024 outlay and about 58% of operating expenses.
- Forward obligations: about $518 billion in future cloud, computing and infrastructure commitments.
- Customer concentration: two customers each accounted for about 12% of sales.
What is inside the $42 billion loss, and the distance to 2028
Figures as reported from the leaked prospectus, in billions of dollars. Lighter bars are a non-cash charge (left) and a projection (right).
Loss composition, FY2025
Revenue: actual vs 2028 projection
The roughly $34 billion charge relates to financing instruments that could convert into shares. The 2028 figure is the low end of a projected $190 billion to $200 billion range.
Unpacking the $42 billion loss
The headline "$42 billion loss" combines two very different things. Reporting says roughly $34 billion of it is an accounting charge tied to financing instruments that could convert into shares. Charges of this kind typically reflect a change in the fair value of an instrument rather than cash leaving the company, so they generally move with the company's own valuation. That is a reading of the accounting category, and the prospectus itself is the authority on the exact treatment.
Strip that charge out and the operating loss of about $8.06 billion is the figure that describes the core business: revenue of $4.59 billion against operating costs that, by our arithmetic from the reported 58% share, add up to roughly $12.6 billion. Compute alone, at $7.33 billion, exceeded total revenue.
Two readings follow, and both are reasonable:
- The constructive reading: most of the headline loss is non-cash, and the operating loss, while widening, came alongside roughly 12x revenue growth. Heavy up-front compute spending is what a capacity-constrained growth business would be expected to show.
- The cautious reading: an operating loss that grew by about $5 billion in a year, on a cost base dominated by compute, shows how much capital the model requires. The convertible charge also signals that financing terms will matter to public shareholders.
Actual revenue versus run-rate
Earlier coverage of Anthropic cited annualized run-rate figures, such as roughly $9 billion at the end of 2025. The prospectus reports fiscal-year revenue, which is what was actually recognized across twelve months: about $4.59 billion. The two numbers are not in conflict. A run-rate annualizes the latest period, so for a business growing this quickly it will sit well above a trailing-year total. Public-market investors will generally anchor on reported revenue and on how quickly recent quarters convert into it.
A $518 billion compute obligation
The $518 billion in future cloud and infrastructure commitments is about 113 times FY2025 revenue (our arithmetic). Such obligations are typically spread across many years and are often tied to capacity coming online, so the comparison is not a one-year bill. It does show the scale of the bet: the company has committed to compute far ahead of the revenue that would pay for it. The optimistic reading is that demand is outrunning supply and the commitments secure scarce capacity. The cautious reading is that fixed obligations reduce flexibility if growth slows or pricing falls.
Customer concentration
Two customers each represented about 12% of sales, or roughly a quarter of revenue between them. Concentration at that level is common in enterprise and infrastructure businesses, and 12% each is well short of the single-customer dependence some companies disclose. It still means renewals or pricing changes at two accounts could move results noticeably. The prospectus coverage reviewed here does not identify the customers.
The $2 trillion math
The reported valuation rests on projected 2028 revenue of roughly $190 billion to $200 billion. From $4.59 billion, that is about 41 to 44 times in three years, or growth of roughly 3.5x per year, compounded (our arithmetic). Put another way, $2 trillion is about 10 times the projected 2028 revenue, but several hundred times trailing FY2025 revenue.
The valuation is a claim about 2028, not 2025. Investors are being asked to price a revenue base that is roughly forty times larger than today's.
The bull case says the last year already delivered 12x growth, so another three years at a slower multiple is plausible. The bear case says growth rates fall as the base rises, and that the projection depends on demand, pricing and compute supply all cooperating. Neither view can be settled from the prospectus alone.
An existential-risk warning in the risk factors
Forbes reported that the risk-factors section warns Anthropic's AI could pose existential risks to humanity. Risk-factor sections are written to be comprehensive and legally cautious, and Anthropic has long framed safety as central to its mission, so the language is consistent with its public positioning. It is still unusual to see this class of risk stated in an SEC-style disclosure, and it gives future investors and regulators a written baseline to compare against.
What it means
For buyers of AI, the takeaways are practical. Frontier labs run on enormous compute commitments and concentrated revenue, which means pricing, model availability and terms can shift as those pressures play out. Teams that depend on a single provider carry that exposure directly. A model-agnostic layer, the approach behind Metir, lets users switch between providers without rebuilding workflows. That is a portability argument that holds regardless of whether one reads the numbers optimistically or cautiously.
The prospectus is a leaked draft, and figures may change before any final filing. The next milestone is the public filing itself, expected after the November midterms.
Sources:
- Fortune: Anthropic IPO S-1 prospectus income statement
- Fortune: Anthropic leaked IPO prospectus, losses and growth
- Yahoo Finance (Reuters): Anthropic prospectus shows $2 trillion target
- Forbes: Anthropic IPO prospectus warns its AI could pose existential risks to humanity
- Technology.org: Anthropic IPO prospectus, $42 billion loss, $2 trillion valuation
Image credits
- Dario Amodei at TechCrunch Disrupt 2023 (hero). Photo: TechCrunch, licensed CC BY 2.0. Wikimedia Commons
- New York Stock Exchange Broad Street facade. Photo: Jakub Hałun, licensed CC BY 4.0. Wikimedia Commons