On November 2, 2026, Palantir reported third-quarter results with revenue of $2.313 billion, up 96% year over year and 20% sequentially. It was the first quarter in the company's history above $2 billion, and it beat the $2.18 billion analysts had expected, according to LSEG figures cited by CNBC. The more structural headline sits one level down: US commercial revenue of $984 million surpassed US government revenue of $953 million for the first time, a reversal of the mix the company was built on.
This post walks through what was reported, what changed since the second quarter (covered in our Q2 2026 analysis), and which parts of the picture the headline numbers do not settle. Where a figure is our own arithmetic rather than a reported number, it is labelled as such.
The crossover, in numbers
US commercial revenue grew 148% year over year and 29% sequentially, from $764 million in Q2 to $984 million. US government revenue grew 96% year over year and 18% sequentially, from $809 million to $953 million. In Q2, government led commercial by $45 million; in Q3 commercial led by $31 million. CNBC noted that US commercial revenue has more than quintupled over two years.
The crossover: US commercial passes US government
Palantir quarterly revenue by US segment, in millions of dollars. Commercial rose 29% quarter over quarter; government rose 18%.
Sources: Palantir Q2 2026 and Q3 2026 earnings releases (SEC filings).
Two points of context keep the milestone in proportion. First, government did not shrink or stall: it accelerated slightly (96% year over year, against 90% in Q2). The crossover is commercial growing faster, not government weakening. Second, by our own calculation, US commercial was about 50.8% of US revenue ($984 million of $1.937 billion) versus about 48.6% in Q2 ($764 million of $1.573 billion, summing the two US segments). The share shift is real but modest in a single quarter; it is the compounding over several quarters that would make the business look structurally different.
Total US revenue was $1.937 billion, up 119% year over year. By our calculation, the remainder, roughly $376 million, is international revenue ($2.313 billion minus $1.937 billion). Palantir does not break out total commercial and total government in the portion of the release we reviewed, so we do not estimate those.
Profitability: growth without a margin trade-off
Palantir reported GAAP income from operations of $1.085 billion (a 47% margin) and adjusted income from operations of $1.427 billion (a 62% margin). GAAP net income attributable to common stockholders was $1.128 billion (49% margin), compared with about $476 million a year earlier per CNBC. Adjusted free cash flow was $1.216 billion (a 53% margin), and cash, equivalents and US Treasury securities stood at $10.4 billion.
The Rule of 40 is a software shorthand that adds revenue growth to a profit margin; a score above 40 is conventionally considered healthy. Palantir reports its own version: 158%. It is consistent with the inputs (96% growth plus a 62% adjusted operating margin, which sums to 158). The Q2 score was 155% on 93% growth and the same 62% margin. The metric is company-defined and uses an adjusted margin, so it is best read as a trend marker rather than as a like-for-like comparison with other vendors.
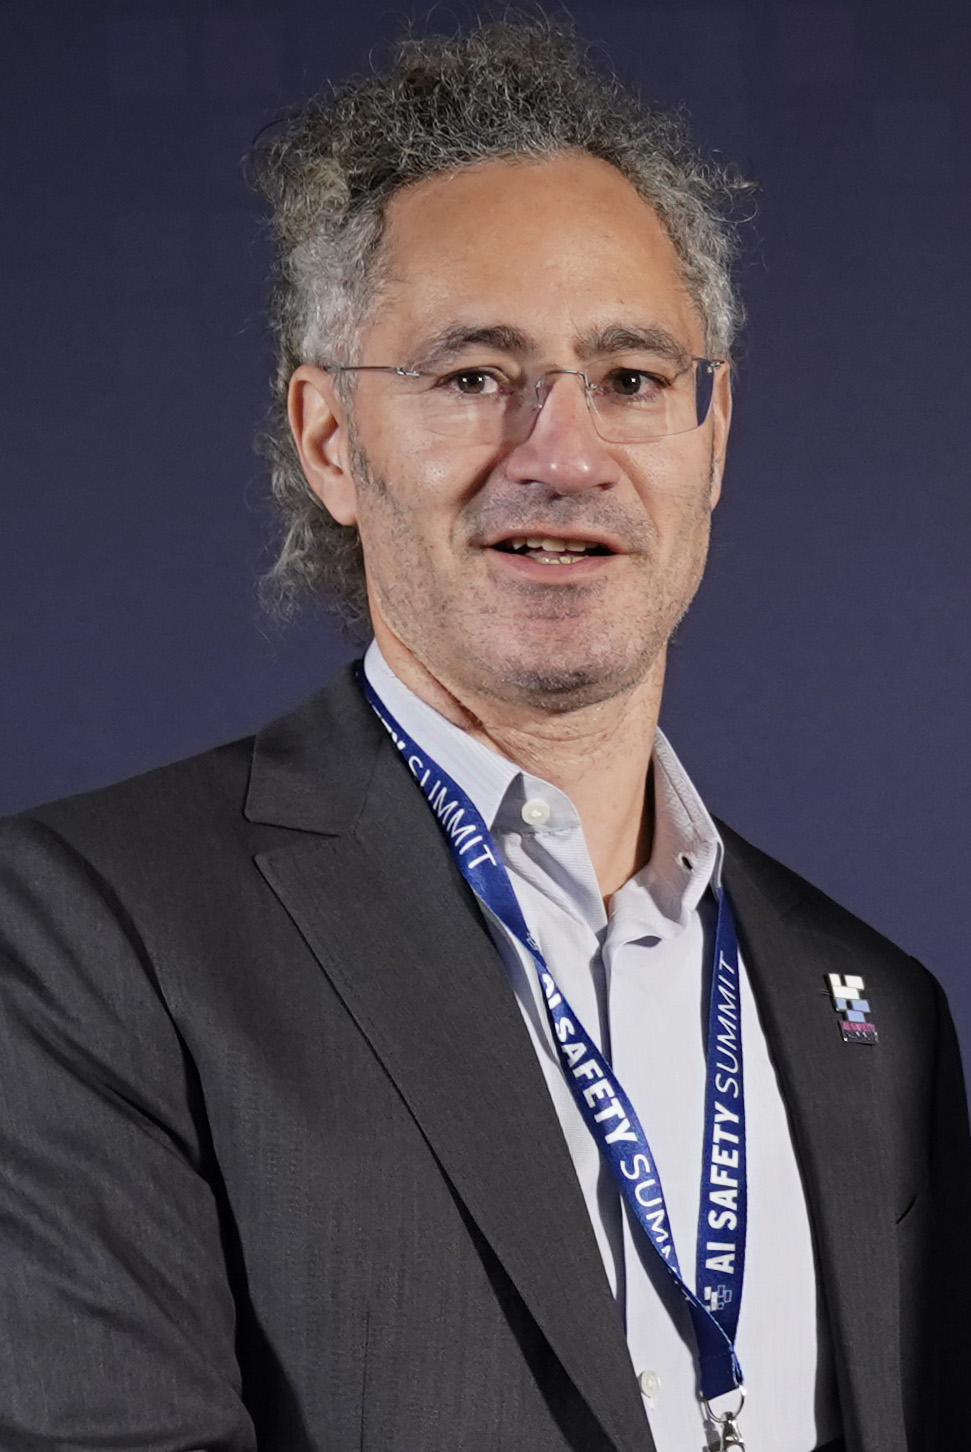
Our U.S. commercial revenue has surpassed our U.S. government revenue for the first time in our company's history.
Alex Karp, Palantir Q3 2026 earnings release
One detail worth noting: adjusted free cash flow margin fell from 63% in Q2 ($1.220 billion on $1.935 billion) to 53% in Q3, even as the dollar amount was nearly flat. Quarterly cash flow can be uneven because of billing and collection timing, and the release does not attribute the change to a single cause, so we treat it as a data point to watch rather than a trend.
Growth durability: the bookings question
Durability is the central debate for a company growing at this rate, and the Q3 release contains evidence on both sides.
- Supportive signals: US commercial remaining deal value (RDV, the contracted value not yet recognized as revenue) was $6.517 billion, up 79% year over year and 4% sequentially. Palantir closed 212 deals of at least $1 million, 107 of at least $5 million and 64 of at least $10 million.
- Cautionary signals: total contract value (TCV) bookings were $2.918 billion, up only 6% year over year, and US commercial TCV was $1.463 billion, up 11%. In Q2, the company reported US commercial TCV of $2.132 billion (up 153%); by our calculation Q3 US commercial TCV is about 31% below that sequential level.
These figures are not contradictory. TCV counts signed contract value in the quarter and is lumpy, since a few very large agreements can swing one period, and it is being compared against a year-earlier quarter that was itself strong. Revenue, by contrast, is recognized over time from contracts signed in earlier quarters, so it can keep growing quickly while new signings normalize. Still, the gap between 96% revenue growth and 6% TCV growth is the clearest quantitative reason to watch whether revenue growth can hold through 2027.
The deal counts show a similar mix against Q2 (220 deals of at least $1 million, 98 of at least $5 million, 70 of at least $10 million): fewer deals at the smallest and largest thresholds, more at the middle one. One quarter of sideways deal counts is not a trend, but it is a reasonable counterweight to the revenue acceleration.
Guidance: what management now expects
Palantir raised its full-year 2026 guidance again.
- Revenue: $8.530 to $8.534 billion, about 91% growth, up from $8.150 to $8.158 billion at Q2 (our calculation: an increase of roughly $0.38 billion at the midpoints).
- US commercial revenue: more than $3.559 billion, at least 143% growth, up from more than $3.424 billion.
- Adjusted income from operations: $5.245 to $5.249 billion.
- Adjusted free cash flow: $4.8 to $5.0 billion, up from $4.5 to $4.7 billion.
- Q4 revenue: $2.649 to $2.653 billion, and Q4 adjusted income from operations of $1.640 to $1.644 billion.
By our calculation, the Q4 revenue guide implies about 14.6% sequential growth from Q3's $2.313 billion, a slower sequential pace than the 20% delivered in Q3. Guidance from this company has historically been exceeded, as Q3 itself showed against its prior $2.160 to $2.164 billion range, but guidance is the company's own estimate and not a forecast we can validate.
CNBC reported shares dipped about 3% in extended trading after the release. We do not attempt a valuation view: the sources we reviewed do not provide a sourced multiple, and a price-to-sales ratio computed against a moving share price would age within days.
Scenarios to watch
The report supports more than one reading, and the next few quarters will separate them.
- Commercial momentum persists. RDV growth of 79% suggests a large contracted backlog still converting to revenue. If TCV re-accelerates, the revenue trajectory looks durable.
- Normalization. If TCV stays in the single digits to low double digits while revenue comparisons toughen, growth rates would decline from here even in a healthy business. Revenue growth of 90%-plus is arithmetically harder each quarter on a larger base.
- Government re-weights the mix. The Q3 crossover could reverse in any quarter if a large government contract is recognized, since the two segments are now close in size.
 Palantir
 OpenAI
 Anthropic
 NVIDIA
What it signals for enterprise AI
Palantir's results are one of the few audited, large-scale measures of enterprise AI turning into recurring revenue. The commercial crossover suggests buyers outside government are paying for deployed systems, not just experiments. The softer bookings numbers are a reminder that a single vendor's results are not an industry verdict. For teams choosing AI tooling, the durable lesson is portability: the orchestration, permissions and data context that make a model useful tend to outlast any single model release, which is also why model-agnostic workspaces such as Metir treat the model as a swappable input.
Sources:
- Palantir (PLTR) earnings Q3 2026, CNBC
- Palantir Technologies Q3 2026 earnings press release (Form 8-K, Exhibit 99.1), SEC EDGAR
- Palantir Technologies Q2 2026 earnings press release (Form 8-K, Exhibit 99.1), SEC EDGAR
- Palantir Q2 2026 earnings, CNBC
Image credits
- Hero and in-body figure: "Alex Karp attends AI Safety Summit" by UK Government, licensed CC BY 2.0, via Wikimedia Commons. Retrieved August 6, 2026, reused here and visually reviewed before use. The image shows Palantir CEO Alex Karp; it is used to illustrate the company and predates the Q3 2026 results discussed here.