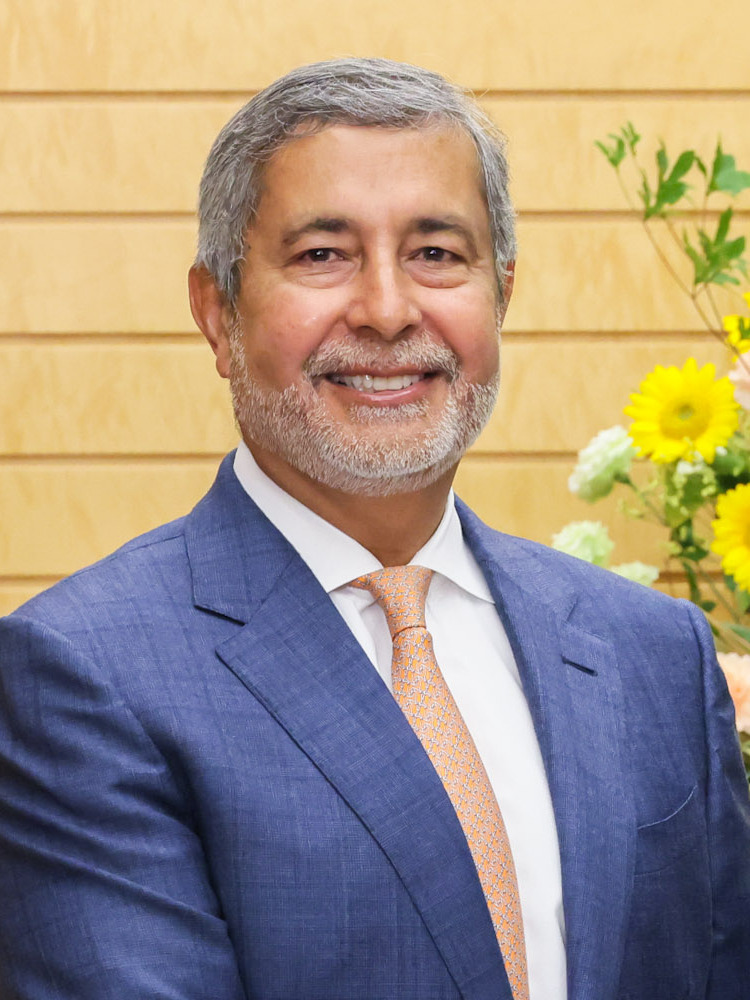
Micron Technology reported fiscal fourth-quarter 2026 results on September 30, 2026, and the numbers read less like a memory company and more like a hypergrowth software business: revenue of $54.23 billion, up 379% from a year earlier, driven by AI-linked memory demand (CNBC). The report is the clearest recent window into the AI memory supercycle, the stretch in which DRAM and high-bandwidth memory (HBM) have become as scarce and strategic as the GPUs they feed.
The Micron Q4 FY2026 earnings numbers
Revenue beat analyst estimates by roughly 7.5% (CNBC; 24/7 Wall St.). GAAP net income was $37.70 billion, or $32.87 per diluted share, while non-GAAP net income was $38.40 billion, or $33.42 per share (Quartz; Investing.com).
For the full fiscal year, revenue reached $133.19 billion, up 256% from $37.38 billion in fiscal 2025. DRAM alone passed $100 billion for the year ($100.68 billion), and NAND contributed $31.79 billion (Quartz).
| Metric | Fiscal 2026 | Comparison |
|---|---|---|
| Q4 revenue | $54.23B | Up 379% year over year |
| Full-year revenue | $133.19B | Up 256% from $37.38B |
| Full-year DRAM revenue | $100.68B | First year above $100B |
| Full-year NAND revenue | $31.79B | Not broken out for growth |
| Q4 GAAP net income | $37.70B | $32.87 per diluted share |
Why memory became the AI bottleneck
A GPU can only compute on data it can reach. Large AI models keep billions of parameters and long context caches in memory, and the processor stalls if memory cannot deliver them fast enough. HBM addresses this by stacking DRAM dies and placing them next to the accelerator, trading the low cost per bit of commodity DRAM for far higher bandwidth. That is general industry background rather than a figure from the earnings report, but it explains the pattern in Micron's results: NVIDIA-class accelerators need memory attached to every package, so AI buildouts pull on memory supply directly.
 NVIDIA
Micron said HBM revenue grew faster than total revenue, and CEO Sanjay Mehrotra pointed to a "strong roadmap for future HBM products" (Investing.com; CNBC).
HBM revenue grew faster than total revenue, which itself grew 379% in a year.
Micron fiscal Q4 2026 results, via Investing.com and CNBC
What custom HBM with Nvidia means
Mehrotra said Micron is working with Nvidia on the industry's "first custom HBM implementation" (CNBC). In standard HBM, the stack's base die is generic. A custom implementation tailors that part of the stack to one customer's accelerator design. The practical effect is tighter integration and a harder product to swap out, which tends to move memory away from commodity pricing. The company has not published pricing terms for such products in the sources reviewed here.
What 83% to 90% gross margins imply
Micron's Core Data Center Business Unit earned $18.0 billion, or 33% of total revenue, at roughly 90% gross margin. The Cloud Memory Business Unit earned $16.3 billion, or 30% of revenue, at roughly 83% (Investing.com).
| Business unit | Q4 revenue | Share of total | Gross margin |
|---|---|---|---|
| Core Data Center | $18.0B | 33% | About 90% |
| Cloud Memory | $16.3B | 30% | About 83% |
Two data-center units earned 63% of the quarter's revenue
Micron fiscal Q4 2026 revenue by business unit, in billions of US dollars, with reported gross margin (GM).
Core Data Center and Cloud Memory together were $34.3B of $54.23B total. The remainder is derived by subtraction. Source: Investing.com.
Margins like these are unusual for a manufacturer with heavy fabrication costs. In an oversupplied market, memory makers compete on price and margins compress. Margins this high are consistent with the opposite condition: demand outrunning supply, which is how the Investing.com coverage describes the quarter ("supply tightness"). The share of revenue coming from just two data-center units, 63% combined, also shows how far the mix has shifted toward AI infrastructure.
The cyclicality question
Memory has historically been one of the most cyclical corners of semiconductors, with shortages followed by capacity additions and then price declines. Nothing in the reported figures settles whether this cycle breaks that pattern. The reported results show tightness today, and the guidance extends it: Micron expects fiscal Q1 2027 revenue of $61.5 billion, plus or minus $1.5 billion, and adjusted EPS of $38.15, plus or minus $1.00 (Investing.com). The midpoint is about 13% above Q4's $54.23 billion by simple arithmetic. The risks to watch are the ones the cycle has always had: customer capex pauses, new supply coming online, and any shift in how much memory each AI system needs.
What it means for AI builders
Memory economics sit underneath the price of every inference request, so supply tightness and cost per token are linked over time. For teams building on AI, that is one more reason to avoid tying a workflow to a single model or vendor. Platforms like Metir let you switch between models as pricing and capacity shift.
Sources:
- CNBC: Micron Q4 earnings report 2026
- Quartz: Micron Q4 2026 earnings, revenue and AI memory
- Investing.com: Micron FQ4 2026 slides
- 24/7 Wall St.: Micron Technology Q4 2026 earnings
- SEC EDGAR: Micron press release exhibit 99.1
Image credits
- Hero: Sanjay Mehrotra, president and CEO of Micron, 2025 (cropped). Source: Wikimedia Commons, photo by the Prime Minister's Office of Japan, licensed CC BY 4.0.
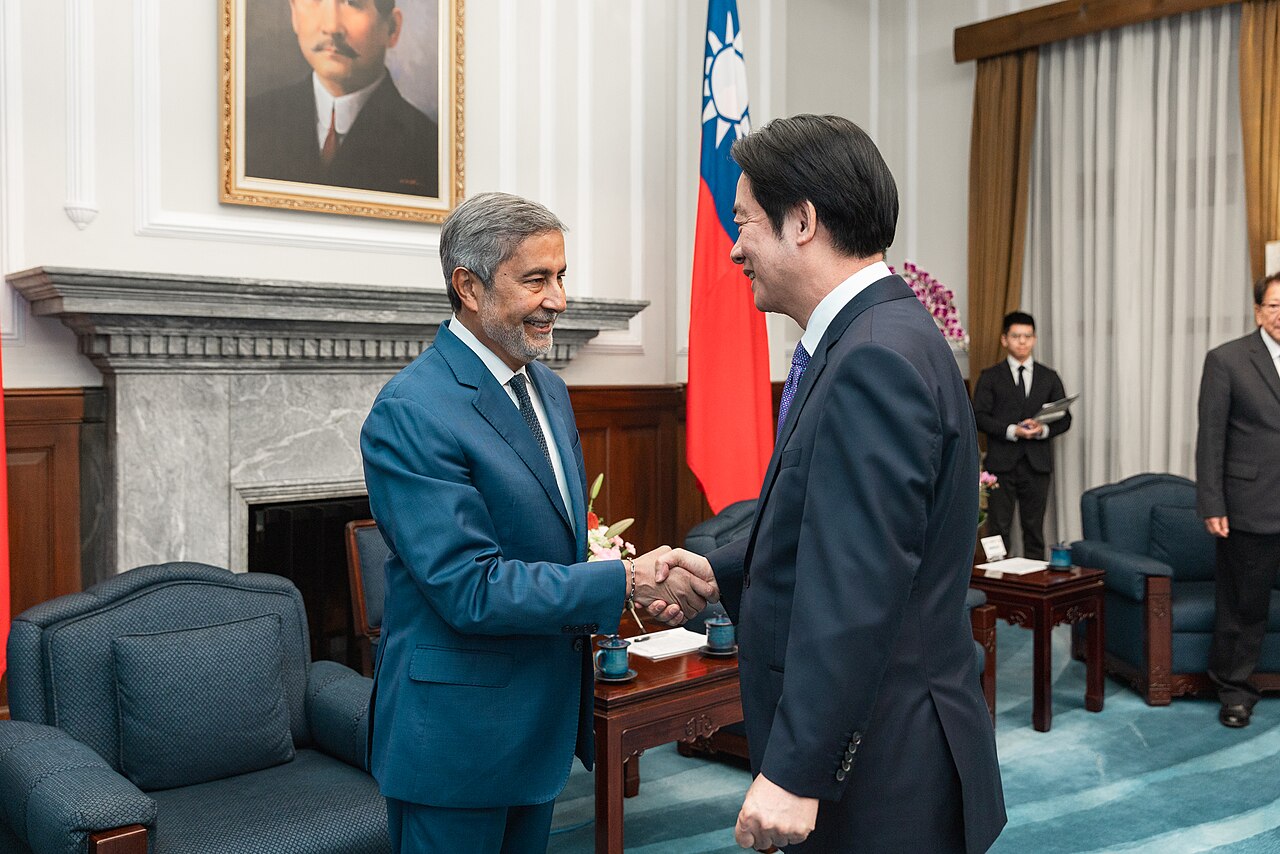
- In-body: Sanjay Mehrotra greeting Taiwan's president at the Presidential Office. Source: Wikimedia Commons, photo by the Taiwan Presidential Office, licensed CC BY 4.0.