On September 16, 2026, the Canadian enterprise-AI company Cohere and Germany's Aleph Alpha signed a definitive agreement to combine, creating what the two describe as the first transatlantic sovereign AI company. The merged business will keep the Cohere name, run from dual headquarters in Toronto and Berlin, and carry a valuation of roughly $20 billion once a concurrent Series E round closes. The deal formalises a combination first outlined in a term sheet back in April, and it is one of the clearest signs yet that a distinct market has formed around AI that governments and regulated industries can run on their own terms.
This piece lays out the structure of the deal, the economics behind the valuation, and why a German national champion has folded into a Canadian company rather than the other way around.
 OpenAI
 Anthropic
 Google
The structure, plainly stated
This is a non-equal merger, not a merger of equals. Cohere leads: its shareholders will hold roughly 90% of the combined company, with Aleph Alpha's shareholders taking about 10%. Cohere brings around $240 million in annual recurring revenue and its Command family of models plus North, its security-first agentic platform. Aleph Alpha, based in Heidelberg, contributes roughly 250 employees, its PhariaAI suite, and specialised strengths in European languages and tokenizer engineering that matter for the regulated European customers both companies court.
The financing is anchored by Germany's Schwarz Group, the retail conglomerate behind Lidl and Kaufland and already an Aleph Alpha backer, which is leading the Series E with about $600 million (EUR 500 million) in structured financing. In return, the merged entity will run on STACKIT, the sovereign cloud operated by Schwarz Digits, giving the combined company a European deployment backbone and giving Schwarz a flagship AI tenant for its cloud.
How the combined company is put together
A non-equal merger: Cohere leads, Aleph Alpha folds in, and a German retail group anchors the financing and the cloud.
The deal is still subject to regulatory approval and is expected to close later in 2026.
The economics of a $20 billion valuation
The headline number deserves scrutiny. Cohere was valued at about $6.8 billion after raising $500 million in August 2025. A roughly $20 billion valuation for the combined company is close to a threefold jump in a little over a year, and on approximately $240 million of annual recurring revenue it implies a revenue multiple in the low 80s. Even in the elevated market of 2026, that is a rich price, and it is not a bet on current sales.
A roughly threefold jump in about a year
Cohere valuation, in billions of US dollars, standalone versus the combined entity.
On about $240M in annual recurring revenue, a $20B valuation implies a multiple in the low 80s, rich even by 2026 enterprise-AI standards and a bet on the sovereign-AI thesis rather than current sales.
What the price is really buying is a thesis. The combined company is positioning itself as the credible non-American, non-Chinese option for organisations that cannot or will not send their data to a US hyperscaler: defence, energy, finance, healthcare, manufacturing, telecommunications and government. Cohere has leaned into this deliberately, avoiding the consumer chatbot race entirely and building instead for private deployment, with customers able to run its models on-premises or in a private or sovereign cloud. Aleph Alpha spent years as Europe's designated sovereign-AI hope with a smaller commercial footprint, reportedly valued at roughly EUR 500 million in its 2023 round. Folding it into a company with real enterprise revenue is an attempt to turn a policy ambition into a going concern.
Cohere will become a Canadian-German company.
Aidan Gomez, Cohere CEO
The sovereign framing also explains the geography. Rather than one company acquiring another and absorbing its identity, the deal is structured to keep a genuine presence on both sides of the Atlantic, because the value proposition depends on it. A customer in Berlin or Ottawa buying "sovereign" AI wants a vendor with local legal presence, local data residency and local political standing, not a foreign firm with a sales office. The dual-headquarters structure is a feature of the product, not an accident of the negotiation.
Why Aleph Alpha folded in
The direction of the combination tells its own story about European AI. Aleph Alpha was for years held up as the continent's answer to OpenAI, but building frontier models is expensive, and a company competing on raw model capability against labs raising tens of billions of dollars faces an uphill economic fight. Over the past two years Aleph Alpha repositioned away from chasing the largest models and toward the tooling, governance and deployment layer that regulated buyers actually purchase. The merger completes that pivot: rather than fund another capital-intensive model-training race alone, it joins a company that already sells to enterprises and pairs its European credentials with Cohere's revenue base and Schwarz's capital.
For the broader European AI conversation, the deal is double-edged. It creates a better-capitalised sovereign champion with real customers, which is what policymakers have said they wanted. It also means the continent's most prominent independent lab now sits inside a company led from Toronto, a reminder that scale in this market is hard to reach from any single national base. The combined company still faces the same durability test every enterprise-AI vendor faces: a rich valuation has to be grown into with recurring revenue, and sovereign positioning wins deals only as long as the underlying models stay competitive with the frontier.
The takeaway
What is verifiable is the shape of the deal: a definitive agreement to combine Cohere and Aleph Alpha into a dual-headquartered company valued near $20 billion, roughly 90% owned by Cohere's shareholders, financed by a Schwarz-led Series E of about $600 million, and running on a European sovereign cloud. It is a bet that data control and regulatory alignment are a durable buying criterion, not a passing preference, for the industries that cannot simply default to a US provider.
That bet points at a lesson that applies well beyond this one merger. For enterprises, where and how a model runs, and who controls the data around it, are becoming as important as which model is marginally smartest this quarter. Keeping the model layer flexible rather than hard-wiring one vendor, the approach platforms like Metir AI take by running Claude, GPT, Gemini and Grok side by side, is the same instinct that makes sovereignty valuable: control over deployment should sit with the buyer, not the supplier. Whether Cohere and Aleph Alpha can grow into a $20 billion price is the open question; that regulated buyers now treat sovereignty as a first-order requirement is the settled part.
Sources:
- Cohere and Aleph Alpha Sign Agreement to Become the First Transatlantic Sovereign AI Solution | PR Newswire
- Cohere and Aleph Alpha sign, with headquarters in Berlin and Toronto | The Next Web
- Cohere valued at around $20B in Aleph Alpha deal | Axios
- Cohere to acquire German AI company Aleph Alpha as it looks to expand in Europe | CNBC
- Why Cohere is merging with Aleph Alpha | TechCrunch
- Cohere's $240M ARR Highlights the Enterprise AI Arms Race | FNEX
- Cohere's Multilingual and Sovereign AI Moat Ahead of a 2026 IPO | Futurum
- Cohere | Wikipedia
Image credits
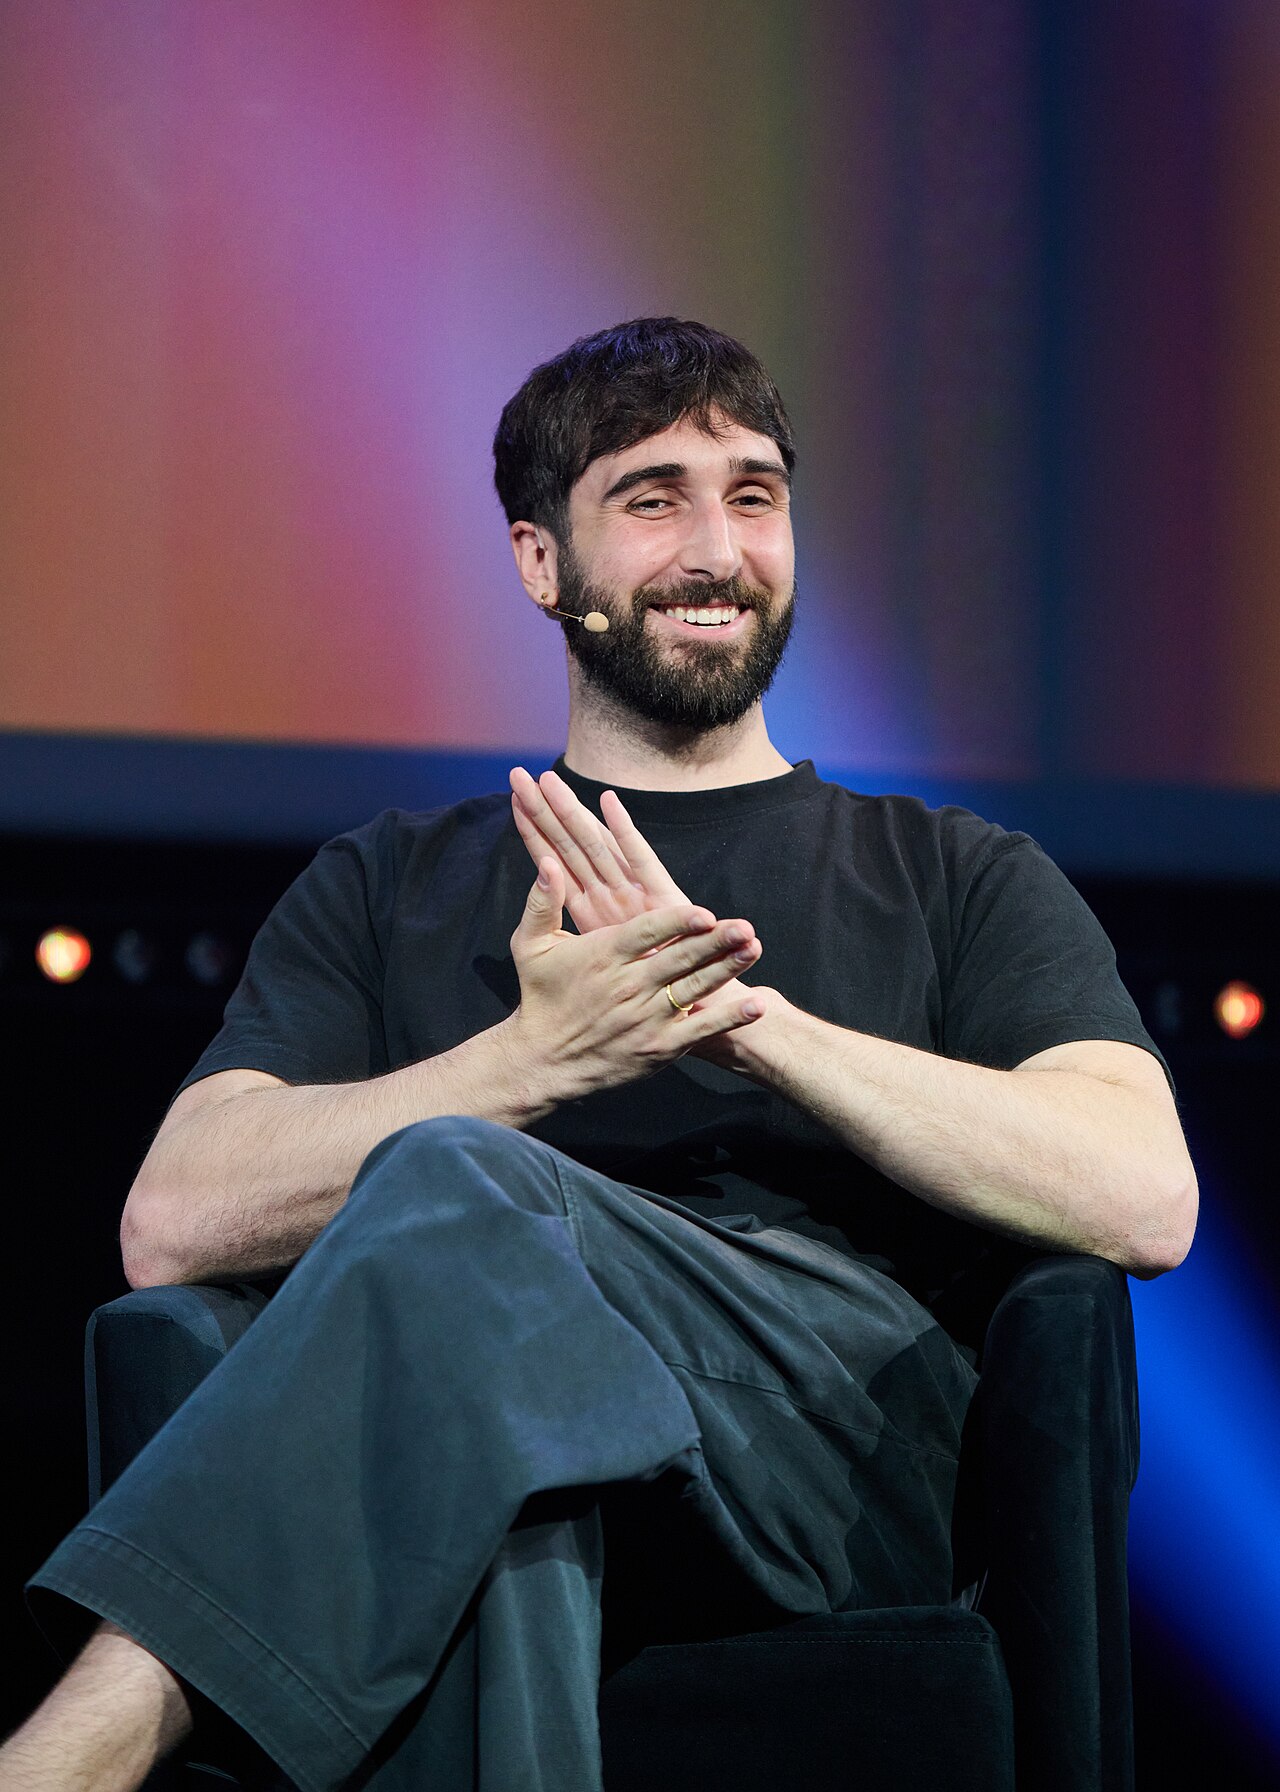
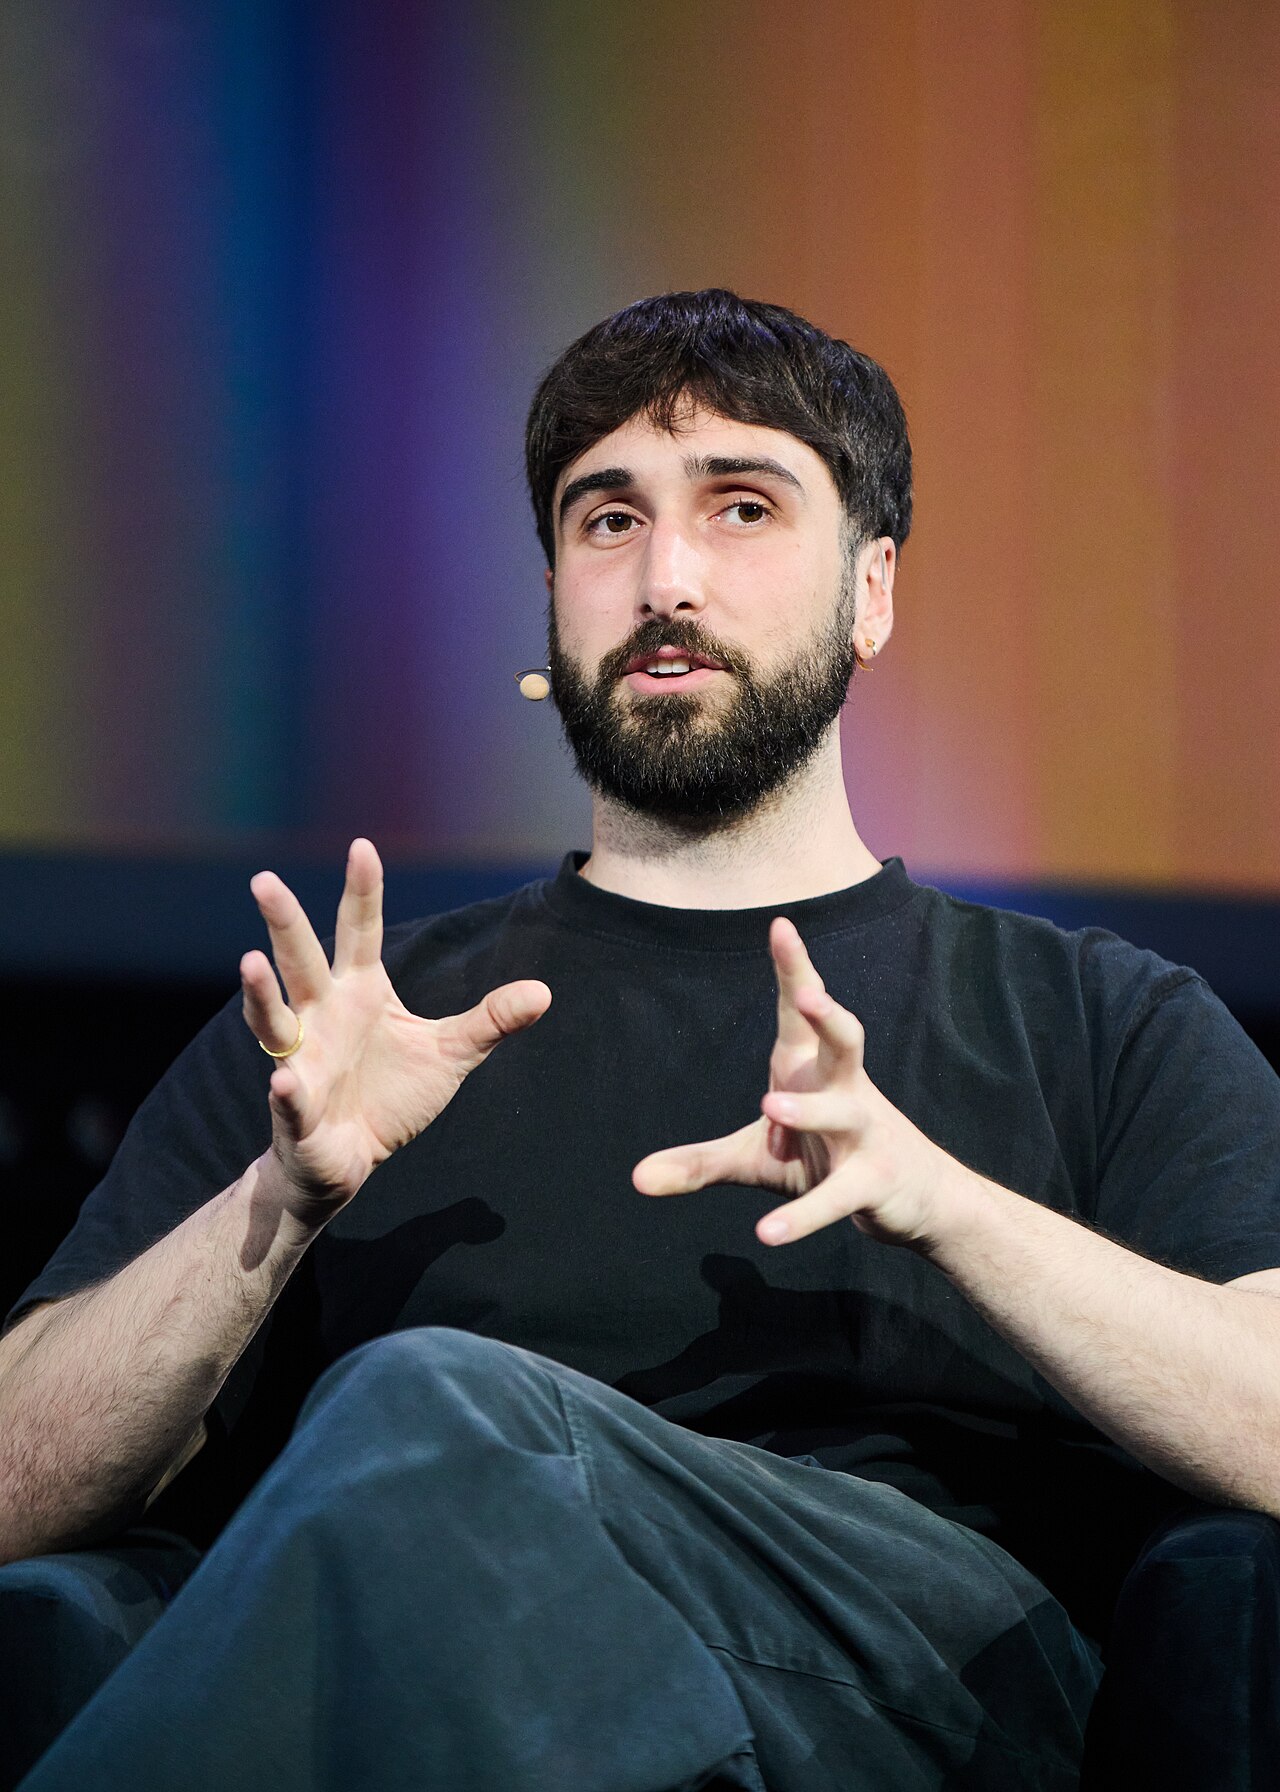
Header image: Cohere CEO Aidan Gomez speaking at the "ALL IN" 2025 conference, via Wikimedia Commons, licensed under CC BY-SA 4.0. In-body photograph of Aidan Gomez at the same event, via Wikimedia Commons, licensed under CC BY-SA 4.0. Both photographs predate the September 2026 merger announcement and show Gomez at a conference.